
Key Points
- Prices rose 3.7% over the 12 months ending September, up from 3.4% in August, as gasoline jumped 9.1% in a single month.
- Social Security benefits will rise 3.6% in January 2027, adding about $75 a month for the average retiree.
- September CPI sets the next I bond inflation rate at 4.08%, so bonds bought by October 31 should earn about 5.00% after their first six months.
Consumer prices rose 0.6% in September on a seasonally adjusted basis, according to the Bureau of Labor Statistics September CPI report released October 14, 2026. Over the past 12 months, the Consumer Price Index climbed 3.7%, up from 3.4% in August. The report is also the last input for Social Security’s 2027 COLA and the next I bond interest rate.
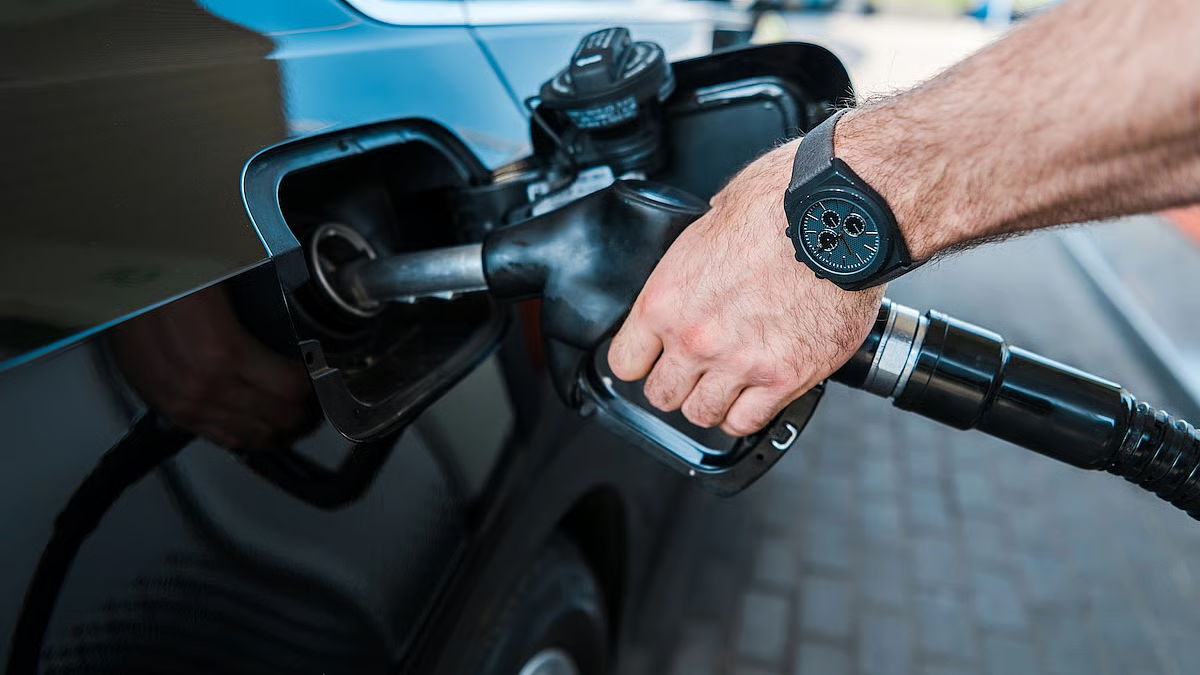
Gasoline was the biggest driver of the increase. The gas index rose 9.1% in September and accounted for more than half of the monthly increase. Energy prices overall are now up 20.4% from a year ago. Core inflation, which strips out food and energy, rose 0.3% for the month and 2.6% for the year.
Why It Matters
Higher prices are shrinking what cash actually earns. Top high-yield savings accounts pay around 4% APY, leaving savers with less than half a point of real return after 3.7% inflation. While higher rates are a boost to savers, it’s still hard to outearn inflation. Groceries were the bright spot, falling 0.1% in September and rising just 1.8% over the year.
Retirees get some relief next year. The Social Security Administration announced a 3.6% COLA for 2027 the same morning, which adds about $75 a month to the average retirement benefit starting in January. That increase is tied to the CPI-W, a version of the Consumer Price Index that tracks wage earners and clerical workers.
What It Means For I Bonds
September CPI locks in the inflation portion of the next I bond rate. Treasury measures the change in CPI-U from March to September, and the index rose from 330.213 in March to 336.940 in September. That works out to a 2.04% six-month increase, or 4.08% annualized, up from the 3.34% rate on bonds issued since May. Here’s how that plays out under Treasury’s composite rate formula:
- Bonds bought by October 31 lock in today’s 0.90% fixed rate, earning 4.26% for six months and then about 5.00%.
- A November purchase gets the 4.08% inflation portion plus whatever new fixed rate Treasury announces November 1.
- Older bonds pick up the 4.08% inflation rate at their next six-month reset, on top of their own fixed rate.
How This Connects
Education prices rose 0.6% in September and 3.8% over the past year, slightly ahead of overall inflation for families already facing a high average cost of college.
Borrowers feel inflation through rates as well. Federal student loan interest rates are set each May from the 10-year Treasury yield, so higher yields next spring would mean higher rates on 2027-28 federal student loans.
What’s Next
The Federal Reserve meets October 27-28 with this report in hand. Treasury announces new I bond rates November 1, and BLS publishes October CPI on November 10. Savers parking cash ahead of those dates can compare today’s best savings rates.
Robert Farrington is the founder of The College Investor and is widely recognized as one of the nation’s leading voices on student loan debt and saving for college. He holds an MBA from UC San Diego Rady School of Management and has spent over 15 years researching, writing, and advising on student loans, 529 plans, financial aid programs, and saving and investing for young professionals.
Robert has been featured in the The New York Times, The Wall Street Journal, The Washington Post, NBC News, and Forbes, where he has been a regular personal finance contributor for over a decade. His work combines both professional expertise and personal experience – he successfully navigated his own student loan repayment journey and has helped thousands of readers do the same.
He is committed to making the intersection of personal finance and education transparent and accessible. You can learn more about Robert on the About Page or on his personal site RobertFarrington.com.
Editorial Disclaimer: Opinions expressed here are author’s alone, not those of any bank, credit card issuer, airlines or hotel chain, or other advertiser and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comment Policy: We invite readers to respond with questions or comments. Comments may be held for moderation and are subject to approval. Comments are solely the opinions of their authors’. The responses in the comments below are not provided or commissioned by any advertiser. Responses have not been reviewed, approved or otherwise endorsed by any company. It is not anyone’s responsibility to ensure all posts and/or questions are answered.
